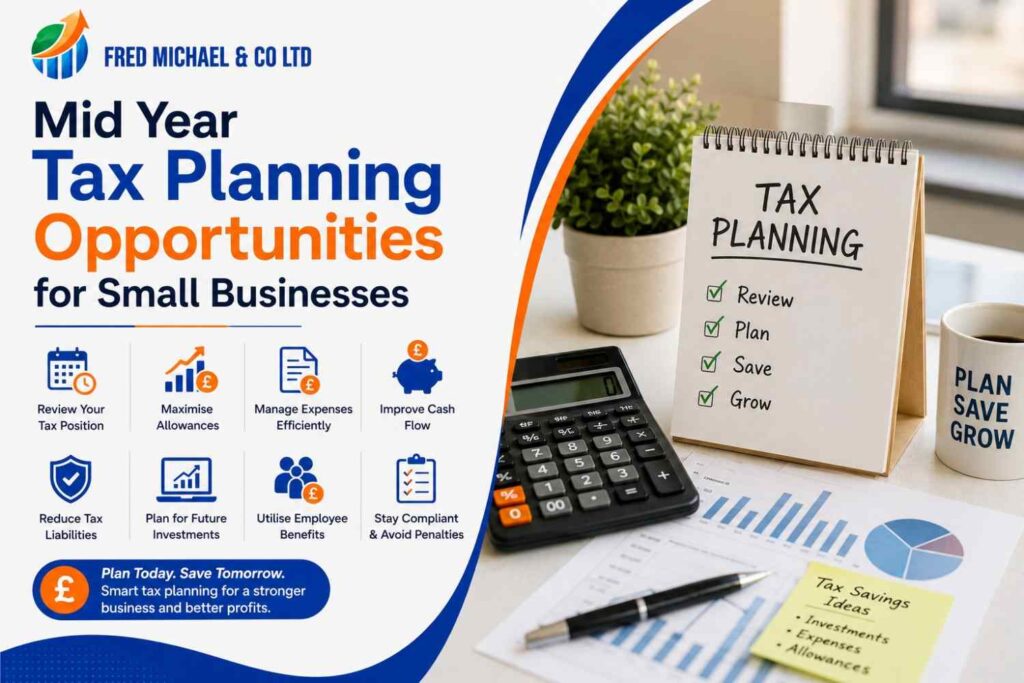
For most small business owners, tax planning becomes an afterthought squeezed into the weeks before a filing deadline but by year-end, many of the most valuable opportunities have already closed. Mid-year tax planning flips this approach: reviewing your finances at the halfway point gives you enough time left to act on what you find, rather than simply reporting on decisions you can no longer change.
This guide walks through the key mid-year tax planning strategies small businesses should be reviewing, why timing matters, and the practical steps that can meaningfully reduce your tax bill before the year closes out. Working with experienced tax return accountants in London at this stage can help surface opportunities that are easy to miss when you’re focused on day-to-day operations.
Why Mid-Year Tax Planning Matters?
Tax planning done at year-end is largely reactive, most of the decisions that shape your tax position (equipment spend, director remuneration, pension contributions) have already been made, so all that’s left is to record the outcome.
A mid-year tax review for small business owners changes the dynamic. With several months still remaining, you have room to adjust spending, restructure how profiaedts are extracted, and make forward-looking decisions that actually influence the final tax bill, the kind of forward planning that quality tax return services in London are built around, rather than a once-a-year filing exercise.
For businesses with a March year-end, a review in September or October roughly the midpoint is often the ideal window. This is exactly the kind of structured check that a good accounting service in London will typically build into its calendar for clients as a matter of routine.
Reviewing Business Structure and Profit Extraction
One of the highest-impact areas of tax planning for small businesses is how profit is extracted from the company. The balance between salary, dividends, and pension contributions has a direct effect on both personal and corporate tax liabilities, and small changes here can add up to meaningful savings over a full year, one of the more effective tax saving tips for small businesses that’s often overlooked.
A mid-year check is a good opportunity to reassess the salary versus dividends split in light of any changes to dividend tax rates or thresholds, confirm whether income is at risk of crossing into a higher personal tax band, review whether a director’s loan account has built up an unexpected balance that could trigger extra tax charges, and consider whether restructuring for example, incorporating a sole trader business still makes sense at current profit levels.
Because these decisions affect both the business and the individual, they’re best reviewed together, which is where a small business financial advisor in London or a Virtual Finance Director in London for businesses with more complex structures can add real value by looking at company and personal tax positions side by side rather than in isolation.
Capital Allowances and the Annual Investment Allowance
If your business has been planning equipment purchases, upgrades, or other capital expenditure, timing matters more than many owners realise. The Annual Investment Allowance (AIA) lets businesses deduct the full cost of qualifying equipment from profits before tax, up to the annual limit, rather than spreading the deduction over several years. Knowing how to reduce tax bills, small business owners often ask about starting right here.
A mid-year review is the right time to ask whether planned purchases could be brought forward into the current tax year to use available allowances, whether the business has already used a significant portion of its AIA limit (meaning further purchases would be better delayed), and whether any assets already purchased haven’t yet been correctly claimed.
Getting this timing right can significantly affect taxable profit for the year, and it’s much easier to adjust in September than in March.
Pension Contributions and Tax-Efficient Extraction
Employer pension contributions remain one of the most tax-efficient ways to extract value from a business, since they’re typically deductible as a business expense while avoiding both income tax and National Insurance for the recipient, within the relevant allowances. This is a core piece of any wider financial planning management in London approach for owner-managed businesses, and good financial planning management in London advice pays for itself many times over.
Mid-year is a sensible point to review how much of the annual pension allowance has been used so far, consider whether increasing employer contributions before year-end would reduce the corporation tax bill, and check whether unused allowances from previous years can still be carried forward.
This is also an area where waiting until the last few weeks of the tax year is genuinely risky, pension contributions need to clear before the year-end cut-off to count, and processing delays are common when everyone acts at once.
Making Use of R&D Tax Credits
Research and Development (R&D) tax relief is frequently overlooked by small businesses that don’t consider themselves to be doing “research,” even though HMRC’s definition is broader than many assume. Any business developing new products, improving processes, or solving technical uncertainties may have a legitimate claim.
A mid-year check helps by identifying qualifying activity while documentation is still easy to gather, estimating the potential value of a claim for cash flow planning, and keeping records in a way that supports a claim at year-end, since R&D claims depend heavily on contemporaneous documentation. Businesses that wait until after year-end often find it far harder to reconstruct the evidence needed.
VAT Threshold and Registration Planning
For growing small businesses, the VAT registration threshold is worth monitoring throughout the year, not just when a return is due. Businesses that cross the threshold must register, but the timing of growth can affect whether voluntary registration earlier might actually be more tax-efficient particularly where a business incurs significant VAT on costs and deals mainly with VAT-registered customers.
A mid-year review should check rolling 12-month turnover against the current threshold, consider whether voluntary registration would allow VAT recovery sooner, and confirm whether a scheme currently in use (such as the flat rate scheme) still suits the business as it grows.
Reviewing Allowable Expenses and Record-Keeping
It sounds basic, but a mid-year review of what’s actually being claimed and how well it’s documented often uncovers gaps that are much easier to fix in real time than to correct retrospectively. Missed allowable expenses are one of the most common reasons small businesses overpay tax, and they undermine even the best tax efficient strategies for small business owners put in place elsewhere.
Worth revisiting at the midpoint of the year: whether home office, mileage, and subsistence claims are being captured consistently; whether Making Tax Digital (MTD) record-keeping is being met in practice, not just theory; and whether receipts and invoices are stored in a way that would hold up under an HMRC enquiry.
Loss Planning and Carry-Forward Considerations
If a business has had a difficult trading period, mid-year is a good time to think about how losses will be used. UK tax rules allow trading losses to be carried back, carried forward, or in some cases set against other income, and the right approach depends heavily on the wider financial picture.
Reviewing this mid-year rather than after the accounts are finalised gives more flexibility to plan around whether carrying losses back to a prior profitable year could generate a repayment, whether it makes more sense to carry them forward against expected future profits, and how loss planning interacts with any planned changes to business structure.
Building a Checklist and Avoiding Common Mistakes
Rather than a one-off exercise, it helps to build a repeatable year end tax planning checklist starting at the midpoint of the year covering profit extraction, capital allowances, pensions, R&D activity, VAT thresholds, expense records, and loss positions. Tracking small business tax deadlines UK alongside its pension cut-offs, AIA limits, VAT registration windows, and the self-assessment deadline helps ensure nothing slips through simply because it wasn’t on the radar until too late.
Several patterns show up repeatedly among small businesses that leave tax planning until year-end:
- Missing the AIA window by making large capital purchases too late to meaningfully affect that year’s tax position.
- Overlooking pension deadlines, only to find processing delays push contributions into the wrong tax year.
- Failing to document R&D activity as it happens, making claims harder to substantiate later.
- Ignoring the VAT threshold until a compulsory registration deadline is imminent.
- Treating tax planning as a once-a-year task, rather than an ongoing process with a structured mid-year checkpoint.
Getting Professional Support
Given how many of these areas overlap with profit extraction, pensions, R&D, VAT, and loss planning all interact, many owners find it more effective to work with a team that sees the whole picture. Reliable tax return services in London paired with proactive advice catch far more than a once-a-year filing exercise. Growing businesses juggling multiple funding and reporting priorities may also benefit from a Virtual Finance Director in London, providing senior-level oversight without a full-time hire’s cost. For year-round support rather than a once-a-year conversation, established tax return accountants in London backed by a dependable accounting service in London and, where it adds value, a specialist small business financial advisor in London can turn mid-year planning into a standing part of how the business is run, not a scramble before the deadline.
Final Thoughts
Small business tax planning UK rules reward businesses that act early, not those that simply report what’s already happened. Mid-year tax planning isn’t about finding loopholes, it’s about making sure decisions already being made throughout the year are made with tax efficiency in mind, while there’s still time to act. Setting aside time at the midpoint of the tax year, ideally alongside an accountant who understands the business, turns tax planning from a once-a-year scramble into a structured, ongoing part of running the business.
Frequently Asked Questions
What is mid-year tax planning for small businesses?
Mid-year tax planning is a review of your business finances at the halfway point of your tax year rather than waiting until year-end so there’s still time to act on opportunities like capital allowances, pension contributions, or profit extraction before the year closes.
When should a small business do a mid-year tax review?
For businesses with a March year-end, September or October is typically the ideal window. The goal is to review at roughly the midpoint of your accounting year, giving you enough runway to implement changes before the deadline.
How can small businesses reduce their tax bill before year-end?
Common levers include reviewing the salary-versus-dividends split, timing capital expenditure to use the AIA, increasing employer pension contributions, checking R&D tax credit eligibility, and reviewing VAT registration status all of which are easier to adjust mid-year than in the final weeks.
What are R&D tax credits and does my business qualify?
R&D tax relief applies to businesses developing new products, improving processes, or solving technical uncertainties HMRC’s definition is broader than many owners assume. A mid-year check helps identify qualifying activity while documentation is still easy to gather.
When should a small business register for VAT?
Businesses must register once rolling 12-month turnover crosses the VAT threshold, but in some cases voluntary registration earlier can be more tax-efficient particularly if the business incurs significant VAT on costs and sells mainly to VAT-registered customers.