Every year, thousands of viable UK businesses apply for finance and get turned down not because their idea is weak, but because they haven’t presented themselves as “bankable.” Lenders aren’t just assessing whether your business is good; they’re assessing whether it’s a safe, predictable, and well-documented risk. For many business owners, this is where working with a professional accounting service in London makes a real difference not to make the numbers look better than they are, but to present them clearly and accurately, in the format lenders expect to see.
This guide walks through what “bankable” actually means, what UK lenders look for, and the practical steps you can take to strengthen your position before you apply.
What Does “Bankable” Actually Mean?
A bankable business is one that a lender can confidently assess, understand, and approve without excessive risk. It’s not necessarily the business with the most exciting product or the biggest growth ambitions, it’s the one that can clearly demonstrate its ability to repay what it borrows. If you’ve ever wondered how to make your business bankable, the answer usually starts here: clarity, consistency, and evidence.
Lenders look at three broad areas when forming this judgement:
- Capacity – Can the business generate enough cash flow to service the debt?
- Character – Is the management team credible, experienced, and organised?
- Collateral/Security – What can back the loan if things go wrong?
A business can be commercially promising and still fail on bankability if it can’t evidence these three things clearly. This is often where proper financial planning management in London businesses invests in pays off, not just at the point of applying for finance, but well before, so the numbers are ready whenever an opportunity or need arises.
Signs Your Business Is Not Loan-Ready
It’s a common misconception that loan rejections are purely about weak financials. In reality, many owners ask “why can’t I get a business loan UK lenders will approve?” and the answer often comes down to presentation and preparation rather than the underlying health of the business. Common signs your business is not loan-ready include:
- Incomplete or inconsistent financial records — Lenders can’t assess what they can’t verify.
- Unclear use of funds — Vague explanations of how the money will be spent raise red flags.
- Poor cash flow visibility — Even profitable businesses can appear risky if cash flow isn’t clearly forecasted.
- Weak or missing business plans — Lenders want to see a coherent strategy, not just numbers.
- No contingency planning — If a lender asks “what happens if revenue drops 20%?” and there’s no answer, that’s a concern.
Recognising these gaps early before a lender points them out is one of the most effective ways to improve your approval odds. It’s also where experienced business financial advisors in London can add genuine value, spotting issues an owner might not notice simply because they’re too close to the day-to-day running of the business.
Documents Needed for a UK Business Loan
Lenders want to see accurate bookkeeping, reconciled accounts, and management information that reflects the current state of the business, not figures from 18 months ago. If your books are behind or inconsistent, it signals disorganisation, even if the business itself is performing well. This is one of the main reasons accounting services for small business owners are so widely used in the run-up to a finance application. Clean records simply move applications through underwriting faster.
At a minimum, most lenders will expect:
- Recent management accounts (ideally within the last 1–3 months)
- Filed annual accounts
- VAT returns
- Bank statements
- Aged debtor and creditor reports
A Clear, Realistic Business Plan
A business plan for lending purposes doesn’t need to be a 40-page document. It needs to answer a few key questions clearly: What does the business do? Who are the customers? What’s the growth trajectory? How will the loan be used, and how will it generate a return? Getting this right is often part of broader accounting and bookkeeping services engagements, since the numbers in your plan need to tie back directly to your actual financial records.
Lenders are wary of plans that read like marketing material. Realistic, evidence-backed projections build more trust than ambitious but unsupported ones.
How to Make a Business Attractive to Lenders
Strong Cash Flow Forecasting
Profit and cash flow are not the same thing, and lenders know this well. A business can be profitable on paper but still struggle to meet monthly loan repayments if cash isn’t timed correctly. A 12-month cash flow forecast ideally stress-tested against a slower sales scenario shows a lender that you understand your own liquidity position.
A Credible Management Team
Lenders lend to people as much as they lend to businesses. Relevant industry experience, a track record of sound decision-making, and a management team that can clearly explain its numbers all contribute to a positive credit assessment. If there are gaps in expertise, addressing them directly rather than hoping they go unnoticed tends to build more confidence.
Appropriate Security or Guarantees
Not all lending requires collateral, but where it does, having a clear picture of available assets, property, equipment, invoices, or personal guarantees speeds up the process considerably. Knowing this in advance also helps you understand which type of finance is realistic for your situation, whether that’s a secured loan, asset finance, invoice finance, or a government-backed scheme.
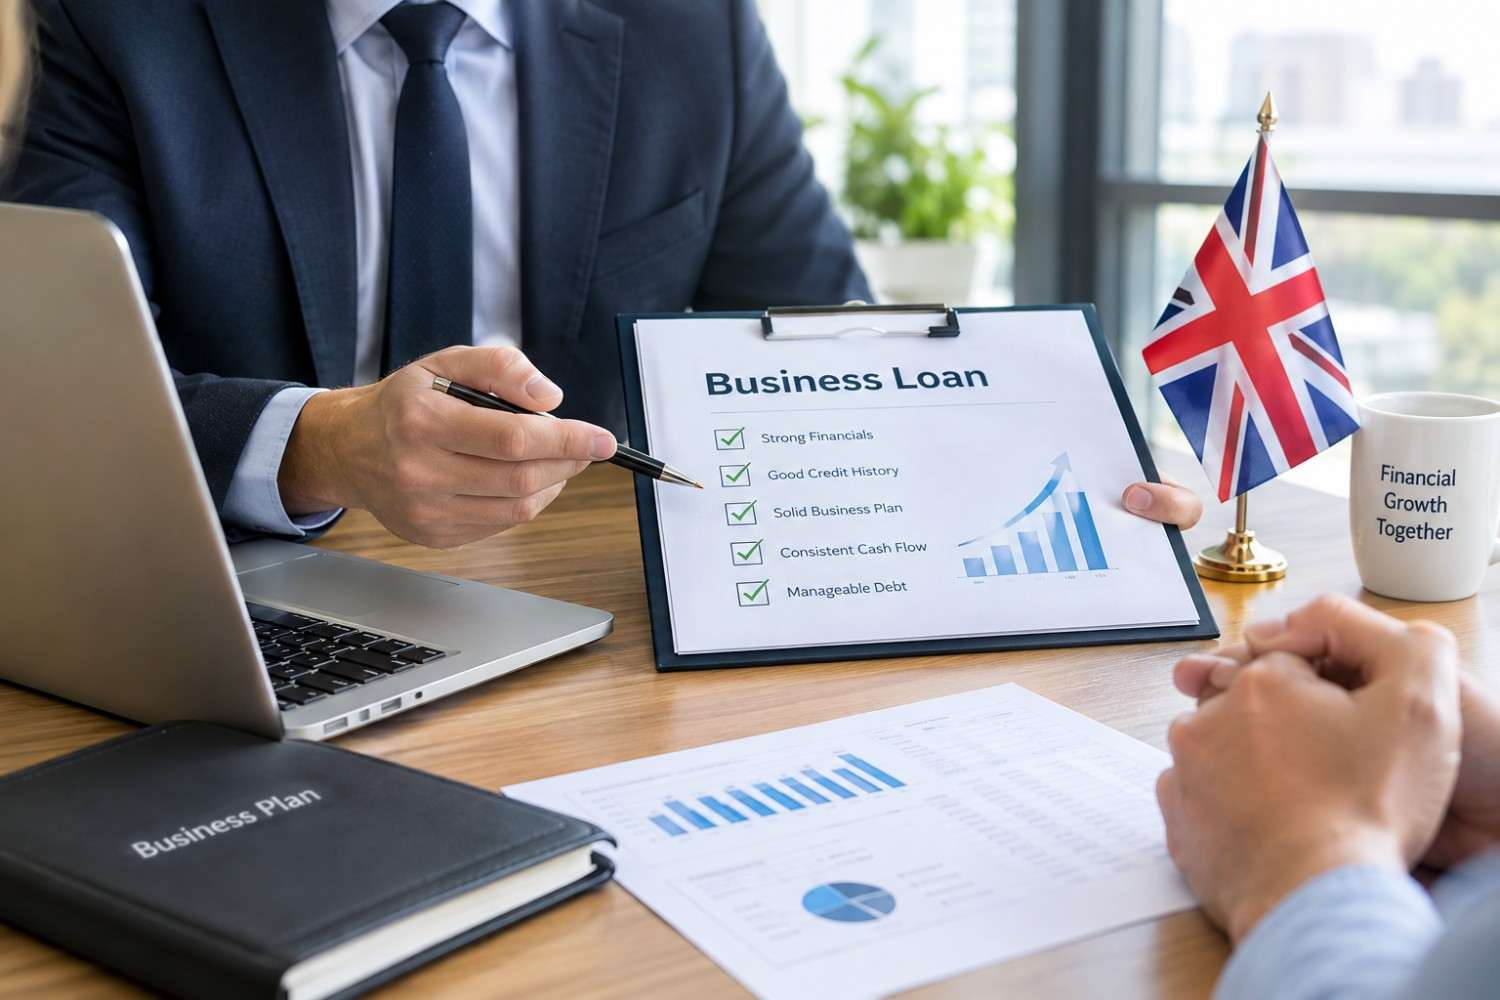
A Defined Debt Service Coverage Ratio (DSCR)
Many lenders calculate a Debt Service Coverage Ratio to determine whether a business generates enough operating income to cover its debt obligations. As a general rule, a DSCR above 1.25 is considered healthy, though this varies by lender and sector. Understanding how DSCR is calculated before you apply puts you in a stronger negotiating position.
Read More: The Missing Link Between Lenders and Bankable Projects
Business Loan Requirements UK Lenders Look For
Get your financial records in order. Start with the basics: reconciled bank accounts, up-to-date bookkeeping, and accurate VAT and tax filings. Lenders move faster and trust applicants more when the numbers are clean and readily available.
Build a 12–24 month financial forecast. A forward-looking forecast, built on realistic assumptions rather than best-case scenarios, demonstrates financial discipline. Include a base case and a downside case so lenders can see you’ve thought about risk, not just opportunity.
Understand your own numbers. Before meeting a lender, know your gross margin, net margin, monthly burn rate (if applicable), and existing debt obligations. Being able to answer financial questions confidently without needing to check a spreadsheet signals competence.
Match the finance type to the need. Not all funding needs are the same, and not all lending products fit every situation. Short-term working capital needs are usually better suited to invoice finance or a revolving credit facility, while long-term investment (equipment, property, expansion) often fits better with a term loan or asset finance. Applying for the wrong type of finance is a common and avoidable reason for rejection.
Consider government-backed schemes. Schemes such as those administered through the British Business Bank exist specifically to support smaller UK businesses that may not fit traditional lending criteria. These can offer more flexible terms, particularly for businesses with limited trading history or lower levels of security.
Don’t overlook your personal tax position. If you’re a sole trader, partner, or director drawing income from the business, your own financial affairs are often scrutinised alongside the company’s. Sound self employed tax planning in UK businesses can strengthen your overall financial profile and demonstrate consistency between your personal and business finances, something lenders do notice.
Address weaknesses before a lender finds them. If there’s a gap, a bad trading year, a thin balance sheet, a new management team addresses it directly in your application with context and a plan, rather than leaving a lender to find it and draw their own conclusions.
Ways to Improve Your Chances of Getting Business Finance
Even experienced business owners can miss how their financials read from a lender’s perspective. Having accounts and forecasts reviewed by someone familiar with what lenders are looking for can catch issues with inconsistent figures, unclear cash flow assumptions, missing documentation before they become a reason for rejection. This kind of review is one of the simplest, most practical ways to improve your chances of getting business finance approved on the first attempt.
Read More: Why Good Projects in the UK Struggle to Secure Business Finance?
A Practical Checklist: How to Get a Business Loan Approved UK
Before submitting a finance application, it’s worth confirming you have:
- Up-to-date management accounts and filed annual accounts
- A clear 12-month (minimum) cash flow forecast
- A concise business plan explaining use of funds
- Calculated DSCR and awareness of your borrowing capacity
- A clear picture of available security or guarantees
- An understanding of which finance product actually fits your need
- A short explanation ready for any financial weak points
Working through this list before approaching a lender doesn’t guarantee approval, but it significantly reduces the chances of an easily avoidable rejection.
Final Thoughts
Bankability isn’t about having a perfect business, it’s about being able to clearly demonstrate, with evidence, that your business is a manageable and predictable risk. Clean financial records, realistic forecasting, and a clear understanding of your own numbers go a long way toward building the confidence a lender needs to say yes.
For many business owners, the hardest part isn’t running the business, it’s stepping back and viewing it the way a lender will. If you’d like to support getting your financial records, forecasts, and loan application in the strongest possible shape, Fred Michael & Co Ltd can help you prepare with confidence. Get in touch with Fred Michael & Co Ltd today to talk through your next steps.