Payroll is the process of paying your employees accurately and on time while meeting every tax and reporting duty that comes with it. The moment you hire your first member of staff in the UK, it becomes one of your most important responsibilities. Get it right, and your team is paid correctly and HMRC is satisfied. Get it wrong, and you risk penalties, unhappy employees, and hours of admin spent untangling mistakes. If you have ever wondered how payroll processing works, this guide explains what payroll is, how it works step by step, which taxes are involved, and how to choose the best way to run it.
What Is Payroll?
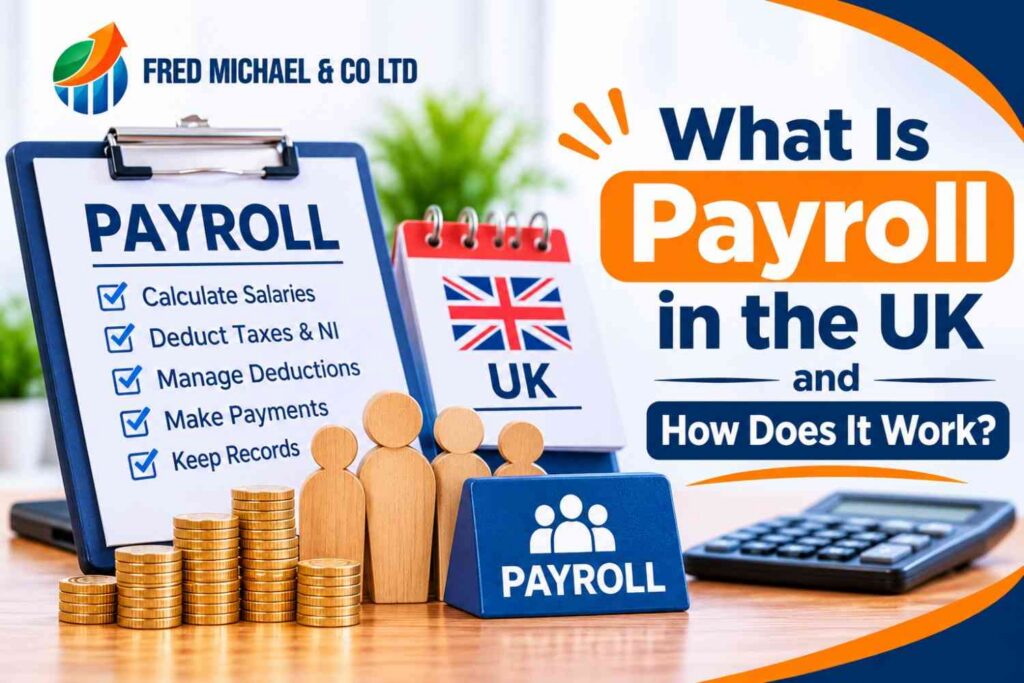
Payroll is how a business calculates and pays its employees’ wages each pay period, whether weekly, fortnightly, four-weekly, or monthly. It is far more than moving money into bank accounts, which is why many owners rely on accounting and bookkeeping services to keep earnings, deductions, and reports in order. A trusted provider of Payroll Services London businesses use will track earnings, work out deductions, produce payslips, and report to HMRC. Payroll services for small business London owners need are built around that same cycle, while payroll management services London firms provide go further by overseeing every run, and an accounting service in London can link the results to your wider records. So, what is included in payroll each time you run it? You are responsible for:
- Calculating each employee’s gross pay, including overtime, bonuses, holiday pay, and statutory payments
- Deducting income tax and National Insurance contributions
- Applying other deductions, such as pension contributions or student loan repayments
- Reporting pay and deductions to HMRC
- Paying your employees, and then paying HMRC what you owe
It is worth separating two ideas that are often confused. Salary is what an employee earns; payroll is the process of calculating, deducting, and paying that salary with all the tax obligations attached. The same clarity applies to gross pay vs net pay UK employers handle every month: gross pay is the total earned before deductions, and net pay is what reaches the employee’s bank account. Strong Bookkeeping and Accounting Services make this distinction easy to track, and outsourced payroll services London employers choose can manage it from end to end. Business payroll services London teams offer, together with accounting services for small business and outsourced accounting services, keep this data flowing cleanly into your accounts.
Payroll also protects your reputation. Employees expect to be paid the right amount on the right day, and consistent, accurate payslips build trust and make your business a more attractive place to work. Clean payroll data also supports tax planning and gives you a clear picture of staffing costs.
Who Needs to Run Payroll?
If you employ people in the UK, you are generally required to operate the Pay As You Earn system. Anyone asking what PAYE is in the UK should know it is HMRC’s method of collecting income tax and National Insurance directly from wages. In practice, you register as an employer with HMRC before your first payday, set up payroll records, and report every time you pay your staff. Limited company directors who pay themselves a salary may also need to run payroll, even when they are the only employee. At this stage, many owners combine accounting and bookkeeping services with Payroll Services London specialists, and some bring in a virtual finance director in London to support cash flow management and forecasting in London. The right Bookkeeping and Accounting Services partner keeps all of it joined up.
The legal obligations are the same whether you handle payroll yourself, use software, or outsource it. Understanding the payroll compliance requirements UK employers face, such as registering, reporting on time, and keeping records, helps you avoid fines. Building a reliable process early saves a great deal of trouble later.
How Does Payroll Work in the UK?
Here is the UK payroll process explained in simple terms. What is a payroll tax period? It is the tax month, which runs from the 6th of one month to the 5th of the next. Many employers hand the cycle to outsourced payroll services London specialists, while payroll services for small business London providers or business payroll services London teams can run each cycle for you. Pairing them with an accounting service in London and payroll management services London support keeps every run compliant. Within each pay period, there are five core steps.
Step 1: Keep Accurate Employee Records
Start with the basics: each employee’s name, address, National Insurance number, tax code, pay rate, hours worked, and any statutory sick pay or holiday entitlement. Accurate records make every calculation easier and protect you if HMRC ever asks questions. They also give outsourced accounting services and accounting services for small businesses what they need to work from. They support cash flow management and forecasting in London too, where a virtual finance director in London relies on dependable payroll data.
Step 2: Calculate Gross Pay and Deductions
Work out what each person has earned, then calculate the deductions due. How are wages calculated in the UK? For hourly staff, hours worked are multiplied by the pay rate, with overtime added on top. And how are employee salaries calculated? The annual salary is divided across the pay periods in the year, then adjusted for tax code and deductions. Payroll software automates most of this work, which sharply reduces the risk of error.
Step 3: Produce Payslips
Every employee must receive a payslip showing their gross pay, deductions, and net pay, usually on or before payday. Clear payslips help staff understand what they have been paid and why.
Step 4: Report to HMRC
On or before each payday, you send HMRC a Full Payment Submission (FPS). This confirms what each employee earned and what was deducted in that period. Some employers also send an Employer Payment Summary (EPS) to report adjustments, such as claims for reduced liabilities.
Step 5: Pay Your Employees and HMRC
Net pay is normally sent by bank transfer. You then pay the income tax, National Insurance, and any other amounts you have deducted, plus your own employer contributions, to HMRC by the deadline. Late payments can trigger penalties, so build these dates into your payroll calendar.
Read More: Most Business Owners Find Out They Overpaid Tax After the Deadline Has Passed
Understanding Payroll Deductions
What deductions are taken from salary UK employees see on a payslip? Pre-tax deductions, such as workplace pension contributions under a net pay arrangement, come first. Income tax is then calculated using the employee’s tax code, followed by any voluntary deductions, such as union dues. What remains is net pay.
Income Tax
Employees pay income tax on earnings above their Personal Allowance, which was £12,570 in 2025/26. You deduct it through PAYE according to each person’s tax code. For England, Wales, and Northern Ireland, the 2025/26 bands were:
- Personal Allowance: up to £12,570 at 0%
- Basic rate: £12,571 to £50,270 at 20%
- Higher rate: £50,271 to £125,140 at 40%
- Additional rate: above £125,140 at 45%
Scotland sets its own income tax bands. Rates and thresholds can change, so always check GOV.UK for the figures that apply to the current tax year.
National Insurance Contributions
Both employees and employers pay National Insurance. In 2025/26, employees paid 8% on earnings between £12,570 and £50,270 a year and 2% above that. Employers paid 15% on employee earnings above £96 per week (£417 per month). You deduct the employee share through payroll, add your own contribution, and pay the total to HMRC.
Pensions and Student Loans
Under automatic enrolment, employers must enrol eligible workers into a workplace pension and pay in their own contributions. Student loan repayments are handled in the same way: HMRC issues a notice, or the employee’s starter checklist indicates it, and you deduct the right amount each pay period.
Payroll Taxes and Costs for Employers
Employers carry costs beyond wages. The main one is employer National Insurance, but there are also pension contributions and, for businesses with an annual pay bill above £3 million, the Apprenticeship Levy. Many smaller businesses can reduce their bill through the Employment Allowance, which cuts employer National Insurance by up to £10,500 per tax year. The previous £100,000 cap on eligibility was removed from April 2025, so more employers now qualify. You claim it through your payroll software or HMRC’s Basic PAYE Tools.
Read More: Employment Rights Act for Logistics and Construction Firms: Payroll Risks to Avoid
Manual Payroll vs Automated Payroll: Three Ways to Run Payroll
There is no single right way to run payroll. The best option depends on your size, budget, and how much of the process you want to control.
Manual payroll: You do every calculation yourself using HMRC’s tools and tax tables. It costs little and gives you full control, but it is time-consuming, and the risk of mistakes rises as your team grows.
Payroll software: Software automates calculations, payslips, and HMRC submissions. It balances cost and control, which is why it is popular with growing businesses. The trade-offs are setup time and per-employee fees on some platforms.
Outsourced payroll: A provider or accountancy firm handles calculations, payslips, and filings. It saves time and reduces errors, though it usually costs more.
Digital Record-Keeping and Making Tax Digital
Digital record-keeping is becoming increasingly important for UK businesses. HMRC’s Making Tax Digital for Income Tax is being phased in for sole traders and landlords who meet specific income thresholds, requiring digital records and quarterly updates through compatible software. Professional accounting and bookkeeping services can help businesses maintain accurate digital records, track financial transactions, calculate tax and National Insurance, submit FPS and EPS reports to HMRC, and keep a clear record of every payment.
Common Payroll Mistakes UK Employers Make
Even well-run businesses slip up. The most frequent problems include:
- Using the wrong tax code, so employees pay too much or too little tax
- Missing FPS deadlines, which can trigger late-filing penalties
- Misclassifying workers, such as treating an employee as a contractor
- Forgetting holiday pay or statutory payments owed to staff
- Poor record-keeping, which makes errors hard to trace and defend
Regular checks, a payroll calendar, and a second pair of eyes on every run prevent most of these. A dependable process is an investment, not an overhead.
Get Expert Payroll Support From Fred Michael & Co Ltd
If you would rather spend your time growing your business, expert support makes a real difference. Fred Michael & Co Ltd can help you set up payroll correctly, stay compliant with HMRC, and keep every payslip and submission accurate and on time. Whether you are preparing your first pay run or tired of fixing errors in a system that has outgrown you, our team will review your current setup, explain your options in plain English, and take the pressure off.
Final Thoughts
Payroll is far more than paying wages. It combines accurate records, correct deductions, timely reporting to HMRC, and clear communication with your team. For most growing businesses, the real question is not whether payroll matters but whether the time spent on it is the best use of the owner’s energy.
If you would rather spend that time growing your business, expert support makes a real difference. Fred Michael & Co Ltd can help you set up payroll correctly, stay compliant with HMRC, and keep every payslip and submission accurate and on time. Contact Fred Michael & Co Ltd today to talk through your payroll needs.